Affirm: Buy now, pay over time

Screenshots
Details
- Rating
- 216.04K reviews
- Version
- 3.402.1
- Developer
- Affirm, Inc
Analysis by Norviv
I see Affirm: Buy now, pay over time as a useful way to make a planned purchase easier to manage, not as a reason to spend more than I can afford. Its main appeal is that it lets me review a payment plan before committing, then keep track of the purchase in one place. That can be genuinely helpful when a necessary expense lands at an inconvenient time. The trade-off is just as important: splitting a bill does not make it cheaper, and a payment plan still needs room in a real budget.
What makes the payment choice useful
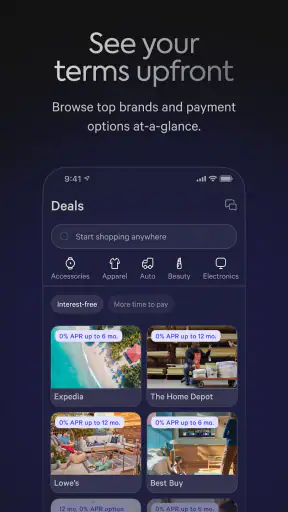
Affirm is a shopping app from Affirm, Inc, and it approaches shopping through financing rather than simply helping me find products or compare store prices. I can browse participating retailers, consider a purchase, and see the proposed terms before accepting them. That advance view is the part I value most. It gives me a chance to pause and decide whether the instalments fit, instead of treating the checkout total as the only figure that matters.
The app’s main audience is someone who already has a specific purchase in mind and wants to understand its repayment schedule. For example, if my laptop stopped working and I needed a replacement for work, I would use the app to check the available plan and compare the instalments with my monthly budget. I would also compare the total cost with paying upfront. If the plan makes the purchase manageable without squeezing out essentials, it may be useful; if it only makes an unnecessary upgrade feel affordable, I would step back.
How I’d use it without losing sight of the total
Before confirming, I’d read the displayed terms carefully, check the payment dates, and make sure the amount due works alongside rent, bills, and other commitments. A practical habit is to note the scheduled payments in the same place I track regular expenses, rather than relying only on a reminder. Reminders can help me remember a due date, but they cannot decide whether I have enough money set aside for it.
I’d also treat each purchase as its own budget decision. Several modest instalments can overlap, making the total amount due in a month larger than any one plan suggests. Looking at the combined commitments—not just the newest monthly payment—is a useful check before taking on another purchase. This is especially relevant around seasonal shopping, when it is easy to make separate decisions that all land on the same household budget.
Getting Started with Affirm
Jumping into Affirm is a breeze. After downloading the app, the setup is pretty straightforward. You just need to sign up, confirm your details, and boom, you're ready to shop. The app has a clean, user-friendly interface that makes navigating your financing options incredibly simple. Trust me, even if you're not tech-savvy, you'll find your way around without a hitch.
Shopping and Financing
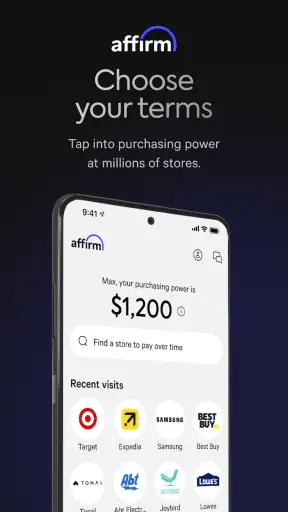
Once you've got the app set up, you can start browsing through a wide array of partner stores. I was amazed at the variety available, from electronics to fashion and even travel. The best part? You can choose to pay over 3, 6, or 12 months. I found this super helpful when I wanted to snag a new laptop but didn’t want to drop all my cash at once.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
It's like having a financial buddy who’s got your back. The app clearly shows you the terms, interest rates, and monthly payments before you commit. No surprises here! Just a heads-up, though—credit approval is required, so make sure your credit score is healthy enough to get the best terms.
That pre-commitment view is worth using as a comparison tool rather than a green light. If I were weighing a laptop against other models or shops, I would compare the full amount payable and the schedule, not just the monthly figure. A lower instalment can come with a longer commitment, so the plan that looks easiest each month is not automatically the best value. I would also check whether the same item is available at a lower cash price elsewhere; financing convenience is less compelling if it leads me to overlook a better total price.
Approval and the offered terms are part of the decision, not a formality to rush through. I would read the actual offer shown for the purchase, since that is what matters for my budget. If the terms are not comfortable, I would leave the checkout and reconsider the purchase, rather than assuming that every item will receive the same plan or that a preferred schedule is guaranteed.
Choosing between Affirm and familiar payment options
Compared with putting a purchase on a credit card, the appeal here is seeing a specific repayment plan for a particular transaction before agreeing to it. A credit card can be more flexible for someone who already manages its balance carefully or earns useful benefits from it; it may also be the simpler choice when the buyer can pay the statement in full. Affirm is more relevant when a shopper wants the planned instalments visible at checkout and has checked how they fit alongside existing obligations.
Paying upfront remains the clearest option when the money is available and doing so will not weaken an emergency cushion. A store’s own payment option may also be worth comparing if it is available, but I would judge both by the complete terms and the total cost, not by a headline monthly amount. Affirm’s strength is the chance to review a defined offer in its app; it is not a guarantee that financing beats cash, a card, or another checkout choice.
Managing Payments
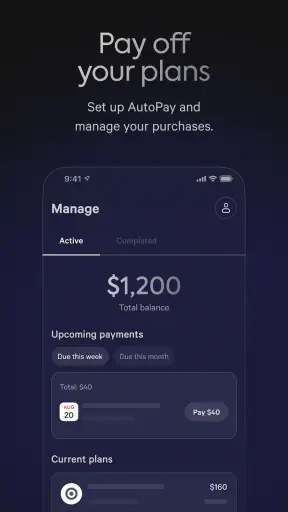
Keeping track of your payments is a piece of cake with Affirm. The app sends you reminders when a payment is due, which is a lifesaver for someone like me who can be forgetful at times. Plus, you can manage everything from the app itself, whether you want to make an early payment or check your remaining balance.
There's something reassuring about having all your payment info at your fingertips. It’s like having a financial dashboard right in your pocket. If you ever have questions, their customer support is just a few taps away.
For a smoother routine, I’d review the balance after a payment and keep a small note of the next due date in my usual calendar or budget app. That gives me a backup if I miss a notification or do not open the shopping app for a while. I would also check the payment details after making an early payment so I understand how the remaining balance and schedule are shown. Those simple habits make a financing app easier to manage, while keeping the responsibility for the dates with me.
There are situations where I would skip this kind of service. If my income is irregular, if I am already juggling several repayments, or if I am not sure I can cover future instalments, adding another commitment could create more stress than convenience. I would also avoid using it to make routine, low-cost shopping feel painless; a series of small plans can obscure how much I have committed overall. In those cases, waiting, choosing a less expensive option, or paying from money already set aside is the more sensible route.
Who gets the most from it
For someone with a stable plan for their spending, the app can make a larger, necessary purchase easier to evaluate. A person replacing an essential household item, for instance, can look at the terms alongside the cash price and decide whether spreading the cost is worth it. The same approach may suit a shopper who prefers to keep a clear schedule for one purchase instead of folding it into a general card balance. In both cases, the benefit comes from careful comparison, not simply from having another way to check out.
The app is free to download, has an Everyone content rating, and has a 4.8 average from around 548,000 ratings. It has more than 10 million installs and was released on June 20, 2016. Version 3.402.1 is listed for devices running Android 7.0 or later. Those details suggest a well-established shopping option, but popularity cannot tell me whether an individual offer is affordable or suitable; I still need to make that call based on the terms in front of me.
My Personal Take
Using Affirm: Buy now, pay over time has been a game-changer for managing my purchases. It’s flexible and transparent, which are two things I really value when it comes to finances. While the interest rates can vary, the app makes it crystal clear what you’re getting into before you hit that "confirm" button.
Overall, I’d say Affirm is perfect if you want to spread out the cost of bigger purchases without any hidden fees sneaking up on you. Just keep in mind that it’s essential to stay on top of your payments to avoid late fees. So, if you’re looking to buy now and pay later, Affirm might just be your new best friend.
My recommendation is narrower than “use it whenever you shop”: I’d consider it for a planned, worthwhile purchase after checking the complete offer, comparing the cash alternative, and confirming that every due date fits my budget. I would not use it to justify buying something I cannot otherwise afford, or stack plans without adding their payments together. With that discipline, its clear checkout terms and in-app payment management can be practical. Without it, the convenience risks making future spending too easy to overlook.
Frequently Asked Questions
01What is Affirm and how does it work?
Affirm is a financial service app that allows users to make purchases and pay for them over time through installment plans. When you choose Affirm at checkout, you can select a payment plan that suits your budget. The app provides transparent terms with no hidden fees, making it easy to manage your finances.
02Does using Affirm affect my credit score?
Affirm performs a soft credit check when you apply, which does not affect your credit score. However, if you choose a longer-term plan, they may conduct a hard inquiry that could impact your score. It’s essential to review the terms and understand how your credit might be affected before proceeding.
03What are the interest rates and fees associated with Affirm?
Affirm offers interest rates ranging from 0% to 30% APR, depending on the retailer and your creditworthiness. There are no late fees, prepayment fees, or hidden charges. It’s crucial to read the terms for each purchase, as interest rates can vary based on the payment plan and merchant.
04How do I make payments with Affirm?
Payments with Affirm can be made directly through its app or website. You can set up automatic payments or make manual payments each month. Affirm provides reminders and notifications to help you stay on track with your payment schedule, ensuring you never miss a due date.
05Is Affirm available for all purchases?
Affirm is available at many online and offline retailers, but not all merchants support it. When shopping, look for the Affirm option at checkout. The app often partners with specific retailers to offer exclusive financing options, so it's worth checking if your favorite stores are included.


